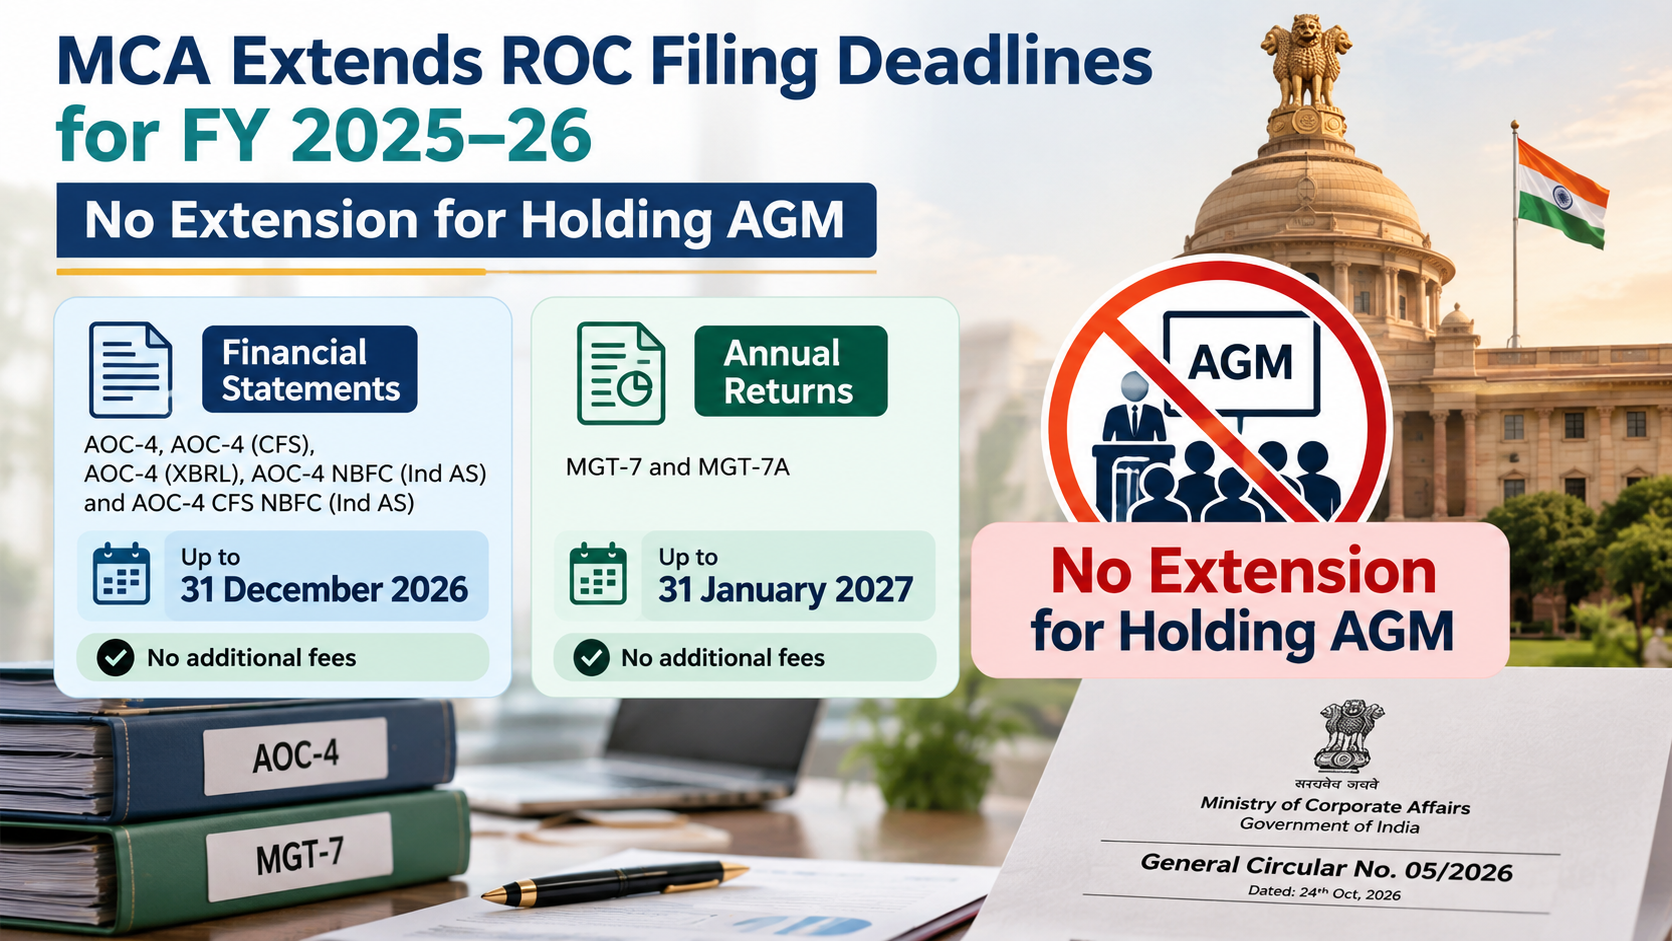
The Ministry of Corporate Affairs has extended the deadlines for filing financial statements and annual returns for the financial year 2025–26, providing relief to companies from additional filing fees. However, the extension does not apply to holding Annual General Meetings (AGMs).
The Ministry of Corporate Affairs (MCA), Government of India, issued General Circular No. 05/2026 dated 24 October 2026, granting additional time to companies to complete specified annual statutory filings under the Companies Act, 2013.
Under the circular, companies may file their financial statements in the prescribed e-forms up to 31 December 2026 and their annual returns up to 31 January 2027, without payment of additional fees.
Importantly, the MCA has expressly clarified that this relaxation does not extend the statutory time limit for holding AGMs. Companies must therefore distinguish between the extended deadlines for filing annual documents with the Registrar of Companies (ROC) and their independent obligation to hold AGMs within the prescribed statutory period.
- MCA General Circular No. 05/2026: Key Relaxations
The circular was issued in response to representations from stakeholders seeking an extension of the due dates for annual statutory filings for FY 2025–26.
The MCA has permitted companies to complete the following filings within the extended deadlines without payment of additional fees.
|
Particulars |
Applicable e-Forms |
Extended deadline |
Additional fees |
|
Filing of financial statements for FY 2025–26 |
AOC-4, AOC-4 (CFS), AOC-4 (XBRL), AOC-4 NBFC (Ind AS) and AOC-4 CFS NBFC (Ind AS) |
31 December 2026 |
Waived within the extended deadline |
|
Filing of annual returns for FY 2025–26 |
MGT-7 and MGT-7A |
31 January 2027 |
Waived within the extended deadline |
These relaxations are expressly provided under paragraph 2 of MCA General Circular No. 05/2026 dated 24 October 2026.
Companies should take advantage of this additional time to complete their annual filings accurately and ensure that the applicable statutory documents are ready for submission.
- Extension for Filing Financial Statements: 31 December 2026
Under Section 137 of the Companies Act, 2013, companies are generally required to file a copy of their financial statements, together with the prescribed documents, with the Registrar of Companies within 30 days of the AGM.
The MCA circular now permits companies to file their financial statements for FY 2025–26 in the specified AOC-4 forms up to 31 December 2026 without payment of additional fees.
The relaxation covers the following forms:
- AOC-4: Filing of financial statements.
- AOC-4 (CFS): Filing of consolidated financial statements.
- AOC-4 (XBRL): Filing of financial statements in XBRL format.
- AOC-4 NBFC (Ind AS): Filing by applicable NBFCs under Ind AS.
- AOC-4 CFS NBFC (Ind AS): Filing of consolidated financial statements by applicable NBFCs under Ind AS.
The applicable form will depend on the nature of the company and its statutory filing requirements.
Companies should note that the relaxation concerns the filing deadline. It does not dispense with the obligation to prepare, approve, adopt or otherwise complete the financial statements in accordance with the Companies Act, 2013.
- Extension for Filing Annual Returns: 31 January 2027
Section 92 of the Companies Act, 2013 deals with the preparation and filing of annual returns.
The annual return contains important particulars concerning the company, including its registered office, business activities, shareholding pattern, members, directors, key managerial personnel and other prescribed information.
Under General Circular No. 05/2026, companies may file their annual returns for FY 2025–26 in the following forms up to 31 January 2027 without payment of additional fees:
- MGT-7: Annual return for companies required to file in this form.
- MGT-7A: Abridged annual return applicable to specified classes of companies, including eligible small companies and One Person Companies, as prescribed.
Companies should verify the form applicable to them and ensure that the particulars disclosed in the annual return are complete and consistent with their statutory records.
The extension provides additional time for completing these filings. It should not be treated as a waiver of the underlying annual return requirements.
- No Extension for Holding the Annual General Meeting
This is the most important clarification in the MCA circular.
The MCA has not extended the statutory deadline for holding AGMs for FY 2025–26.
Paragraph 3 of General Circular No. 05/2026 expressly states that the circular shall not be construed as granting an extension of the statutory time limit for holding AGMs. It further clarifies that companies which have not complied with the relevant statutory timelines will remain liable under the applicable provisions of the Companies Act, 2013.
Section 96 of the Companies Act, 2013 generally requires every company, other than a One Person Company, to hold an AGM every year, subject to the statutory exceptions and requirements.
For an ordinary financial year ending on 31 March 2026, the applicable AGM deadline must be determined under Section 96, taking into account whether the company is holding its first AGM or a subsequent AGM and whether any valid extension has been granted by the Registrar of Companies.
For subsequent AGMs, the general statutory requirement is that the AGM must be held within six months from the close of the financial year, and not more than 15 months must elapse between two AGMs. The Registrar may extend the time for holding an AGM other than the first AGM by a period not exceeding three months, for special reasons.
The MCA’s general circular does not itself grant such an extension.
What does this mean for companies?
A company cannot rely on the extended ROC filing deadlines as a justification for holding its AGM after the applicable statutory deadline.
For example, the fact that a company is permitted to file its financial statements by 31 December 2026 does not mean that it may postpone its AGM until December 2026.
Similarly, the extended deadline of 31 January 2027 for filing the annual return does not extend the time available for holding the AGM.
The distinction is clear: the circular extends specified filing deadlines, not the statutory deadline for holding the AGM.
Companies that have already failed to hold their AGMs within the applicable statutory period should not assume that the circular regularises the default.
- Does the Extension Automatically Regularise Delayed AGM-Related Filings?
No. The extension should be understood within the specific scope of the circular.
The circular permits the specified AOC-4 forms to be filed by 31 December 2026 and MGT-7 or MGT-7A to be filed by 31 January 2027 without additional fees.
However, it expressly preserves the consequences of non-compliance with the statutory AGM timelines.
Companies that have not held their AGMs should therefore examine their circumstances carefully, including the applicable statutory deadlines, the requirements governing the filing of financial statements and annual returns where an AGM has not been held, and any consequences arising from the delay.
The relaxation should not be treated as a blanket exemption from statutory defaults or as an automatic regularisation of an AGM held beyond the prescribed period.
- What Happens if the Forms Are Filed After the Extended Deadlines?
The relaxation is subject to the time limits specified in the circular.
Paragraph 4 clarifies that filings made after the currency of the circular will attract the applicable filing fees, including additional fees, calculated in accordance with the Companies (Registration Offices and Fees) Rules, 2014, from the date on which the filings were actually due under the Act.
Accordingly, companies should not assume that the additional-fee waiver will continue beyond the dates specified in the circular.
The practical deadlines to be observed are:
- 31 December 2026: Deadline for the specified financial statement filings without additional fees.
- 31 January 2027: Deadline for the specified annual return filings without additional fees.
Companies should endeavour to complete their filings within these dates to avoid additional financial exposure.
- Practical Steps for Companies and Directors
In view of the MCA circular, companies should take the following steps:
- Verify AGM compliance: Confirm whether the AGM for the relevant financial year has been held within the applicable statutory period. If it has not, assess the default separately.
- Finalise financial statements: Complete the preparation, audit, Board approval and adoption processes applicable to the company’s financial statements.
- Identify the correct filing forms: Determine whether AOC-4, AOC-4 (CFS), AOC-4 (XBRL), the applicable NBFC form, MGT-7 or MGT-7A is required.
- Complete annual return documentation: Verify the company’s shareholding particulars, director details, registered office information, meeting records and other disclosures required for the annual return.
- File within the extended deadlines: Ensure that the applicable forms are submitted within the dates specified in General Circular No. 05/2026.
- Address existing defaults separately: If the company has failed to hold an AGM within the statutory period or has other outstanding compliance defaults, obtain appropriate professional advice on the steps required under the Companies Act, 2013.
- Conclusion
MCA General Circular No. 05/2026 dated 24 October 2026 provides welcome relief to companies by extending the deadlines for filing financial statements and annual returns for FY 2025–26 without payment of additional fees.
However, the circular must be read carefully and within its stated scope.
The extended deadlines are 31 December 2026 for the specified financial statement filings and 31 January 2027 for annual return filings. Neither date constitutes an extension of the statutory deadline for holding the AGM.
Companies and directors should therefore ensure that AGM compliance is addressed independently and that the relevant annual statutory forms are filed within the extended deadlines.
The key takeaway is simple: additional time has been granted for specified ROC filings, but no general extension has been granted for holding AGMs.
Official Reference: Ministry of Corporate Affairs, Government of India, General Circular No. 05/2026 dated 24 October 2026, titled “Relaxation of additional fees and extension of time for filing of Financial Statements and Annual Returns under the Companies Act, 2013.”
Disclaimer: This article is intended for general informational purposes and should be read in conjunction with the circular and the applicable provisions of the Companies Act, 2013.